Financial Advice (Gen Z Spending Habits)
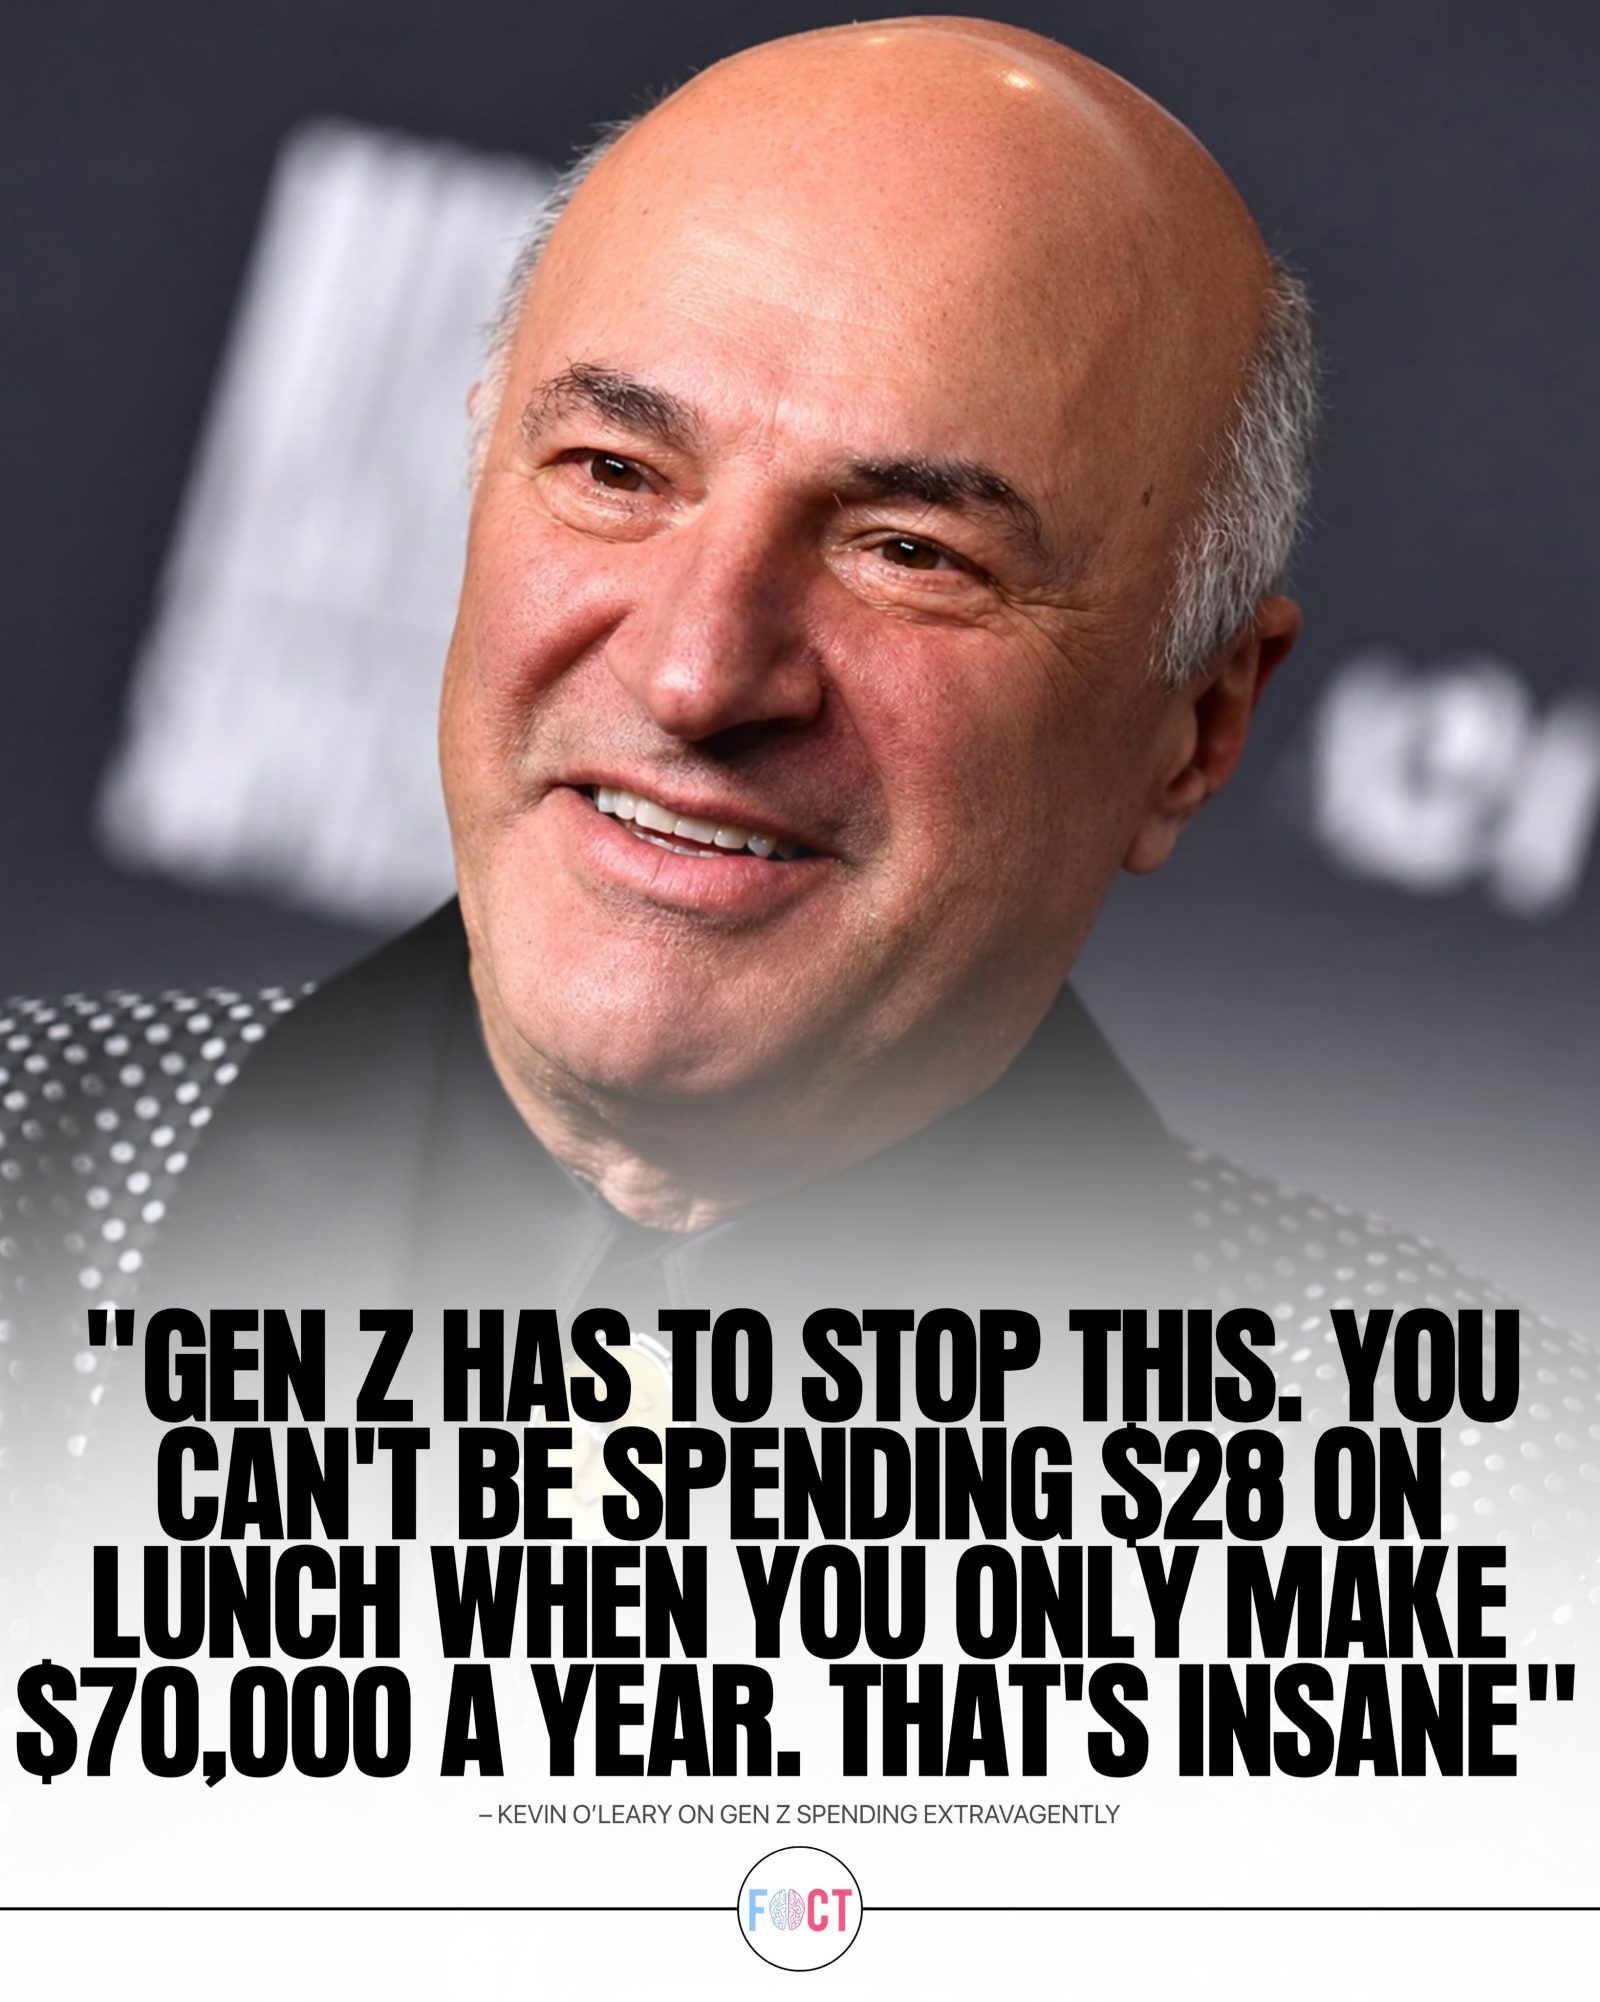
Millennial investor Kevin O’Leary has sparked a debate about financial responsibility among younger workers. His stark critique of Gen Z spending habits, particularly the idea of spending $28 on lunch with a $70,000 salary, has drawn mixed reactions. This stark comment from a well-known investor has reignited conversations about financial discipline and generational spending habits.
Context / Why this matters
Understanding the broader financial context is crucial to evaluating O’Leary's advice. The cost of living has increased significantly over the years, with inflation and living costs affecting everyone, especially younger workers. These factors can make it difficult to save and invest, even for those earning a relatively modest salary. This nuances the debate about spending too much on daily expenses, as O’Leary suggests.
Main discussion
The Controversial Advice
Kevin O’Leary’s controversial advice about Gen Z spending has brought to the forefront a broader conversation about financial responsibility. In a recent interview, O’Leary made a bold statement: “Gen Z has to stop this. You can’t be spending $28 on lunch when you only make $70,000 a year. That’s insane.” This stark comment has drawn considerable attention, with some praising his candor and others criticizing his lack of understanding of current economic realities.
Generational Spending
O’Leary was referring to what he perceives as excessive daily expenses for Gen Zers, such as expensive lunches, coffee, and takeout. Critics argue that these expenses might seem trivial, but for younger people, they can be significant barriers to building long-term wealth.
Daily Expenses
There is no denying that daily expenses can add up. A $28 lunch once a week adds up to $1,456 a year, a tidy sum that could be redirected towards savings or investments. This is a point that O’Leary emphasizes, suggesting that cutting down on such expenses could significantly improve one’s financial health.
Long-Term Wealth
O’Leary’s primary concern is the long-term financial impact of these spending habits. Young people need to understand that small daily expenses can prevent them from building wealth over time. The idea is to save and invest in assets that will grow over time, providing financial security in the future.
The Case for Financial Discipline
O’Leary’s advice is rooted in financial discipline, a concept that has long been promoted by financial advisors. The idea is to live below one’s means, save a significant portion of income, and invest wisely. This approach, when followed consistently, can lead to significant wealth accumulation over time.
Resources and Opportunities
It might not be that simple for some, though. The current economic climate, coupled with stagnant wages, makes it challenging for many to save and invest. The rising costs of housing, healthcare, and education are significant burdens that can prevent even the most disciplined individuals from saving effectively.
Practical tips
Budgeting
Creating a budget is an essential first step toward financial discipline. A budget helps track income and expenses, making it easier to identify areas where spending can be reduced. For young people, this might mean cutting down on daily expenses, such as eating out or buying coffee.
Saving and Investing
Saving a portion of one’s income is crucial for building long-term wealth. This can be done through various means, such as contributing to a retirement account, investing in stocks or mutual funds, or setting up an emergency fund. The key is to start early and be consistent in saving and investing.
Maximizing Earnings
Maximizing earnings is another critical aspect of building wealth. This can be done by negotiating better salaries, seeking promotions, or pursuing side hustles. Higher income levels allow for more significant savings and investments, accelerating wealth accumulation.
Inflation and Living Costs
With inflation and living costs rising, it's essential to make smart financial decisions. Consider budgeting for essentials, looking for discounts, and taking advantage of tax incentives. It's not just about cutting back on luxuries; it's about making every dollar count.
Important takeaways
Balance
Financial discipline is crucial, but it’s also important to find a balance. While it’s essential to save and invest, it’s also necessary to enjoy life. Young people should aim to strike a balance between saving for the future and living in the present.
Context Matters
O’Leary’s advice should be viewed in the context of the current economic climate. While his points about financial discipline are valid, it’s also essential to consider the rising cost of living and inflation. These factors can significantly impact one’s ability to save and invest, making it more challenging for younger people to follow his advice.
Personal Financial Goals
Everyone’s financial situation is unique, and so are their goals. What works for one person might not work for another. It’s essential to tailor financial advice to one's situation and goals, rather than following a one-size-fits-all approach.
Conclusion
Kevin O’Leary’s advice to Gen Z about their spending habits has sparked a broader conversation about financial responsibility and generational spending. While his points about financial discipline and the importance of saving and investing are valid, it’s also essential to consider the current economic climate and the unique challenges faced by younger workers. Young people should aim to balance saving for the future with enjoying the present, tailoring their financial decisions to their unique situations and goals.
Watch the Reel
Questions readers ask
Why did Kevin O'Leary single out a $28 lunch for criticism?
Kevin O'Leary used the $28 lunch as an example to highlight the impact of daily expenses on long-term savings. He argued that such spending can significantly reduce the amount of money Gen Z workers can save and invest, especially on a $70,000 salary.
What is the broader context of Kevin O'Leary's advice to Gen Z?
O'Leary's advice comes amid rising living costs and inflation, which make it challenging for younger workers to save and invest. He encourages them to reassess their daily spending habits to improve their financial outlook.
How much money could a Gen Z worker save by reducing their daily lunch expense?
If a Gen Z worker spends $28 daily on lunch, they would spend approximately $14,000 a year on lunch alone. By reducing this expense, even modestly, they could potentially save thousands of dollars annually.
What are some alternatives to spending $28 on lunch daily?
Alternatives include meal prepping at home, brown-bagging lunch, or exploring more affordable dining options. These changes can lead to significant savings over time and help cultivate better financial habits.
Is O'Leary's advice applicable only to those with a $70,000 salary?
While O'Leary used a $70,000 salary as a reference, his advice can apply to anyone looking to improve their financial discipline. The key takeaway is to be mindful of daily expenses and their long-term impact on savings and investments.
How can understanding inflation help in evaluating O'Leary's advice?
Understanding inflation helps contextualize the increasing cost of living. It shows that even modest salaries may not go as far as they used to, making it crucial for younger workers to be diligent about their spending and savings habits.
What can Gen Z workers do to improve their financial habits according to O'Leary?
O'Leary advises Gen Z workers to reassess their daily spending, such as lunches, and make conscious efforts to save and invest. By being more disciplined, they can better prepare for future financial goals and unexpected expenses.
Related deep dives
Similar reads based on topic and creator.
Recent articles
Fresh deep dives from the latest Reels we unpacked.
Comments
Be the first to comment.