The Canadian Banking Oligopoly and the Call for Open Banking
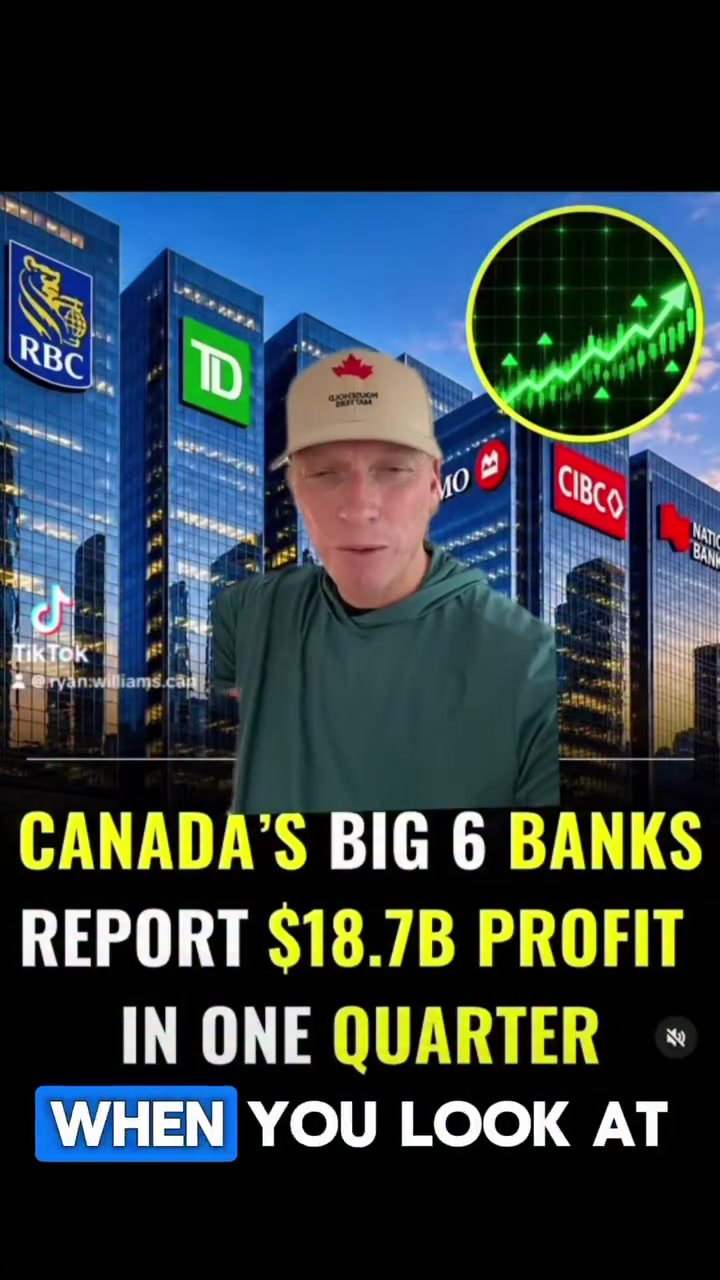
Canada's banking landscape is dominated by a small group of institutions. The Big Six banks — RBC, TD, Scotiabank, BMO, CIBC, and National Bank — control 93% of the market. This concentration of power has significant implications for consumers, as evidenced by the banks' $18.7 billion profit in one quarter alone. This is a stark illustration of a system where a few entities hold immense sway, and open banking is emerging as a potential challenge to their dominance.
The Concentration of Power in Canada's Banking Sector
Open banking is a financial services transformation where financial data is shared securely and electronically. This sharing is done with the consent of the customer and is conducted through secure APIs. The goal is to make all financial products and services interchangeable and portable. This system is a move away from traditional banking, where large institutions have maintained a central and dominant role. In a country as large and diverse as Canada, having a few banks control the majority of the market gives them significant power over consumers, as well as over the entire economy. While this power can enable innovation and efficiency, it also creates potential risks for consumers. Critics argue that concentrated power in the hands of few financial institutions can lead to higher fees, limited service options, and reduced innovation. Moreover, a lack of competition can create an environment where banks prioritize their own interests over those of their customers. Traditional banking models often rely on a set of established practices and services, which may not always be the most consumer-friendly.
Open Banking: The Global Shift Toward Consumer Empowerment
In contrast, open banking is a global trend that empowers consumers by giving them control over their financial data. This model allows customers to share their banking information with third parties, such as fintech companies, through secure and standardized application programming interfaces (APIs). The result is a more competitive and transparent financial landscape, where consumers have more choices and better deals. The UK and Australia already have open banking frameworks in place. The UK mandated open banking in 2018, leading to an average annual savings of £400 per family. This savings can be attributed to increased competition, as well as the ability of consumers to make more informed decisions about their financial products and services. Open banking models enable consumers to compare products and services easily, negotiate better terms, and access a wider range of financial products. In Australia, open banking has also led to more competition and innovation, as well as a more transparent and consumer-focused system.
Open Banking in Canada
While Canadians are known for embracing innovation, open banking is not yet a reality in the country. The federal government has repeatedly delayed the implementation of open banking, despite promises from leaders like Justin Trudeau and Chrystia Freeland to launch it by 2020. As of now, the Canadian government has not provided a clear timeline for when open banking will be implemented. This delay has frustrated advocates who see open banking as a way to improve financial transparency, increase competition, and empower consumers. The lack of open banking in Canada has significant implications for consumers. For instance, competitors like Wealthsimple can offer Canadians 2.4% interest rates on their savings accounts, compared to the paltry 0.2% offered by traditional banks. However, without open banking, competitors face significant barriers to entry, making it difficult for them to challenge the dominance of the Big Six. By allowing consumers to share their financial information with third parties, open banking would enable competitors to offer more innovative and consumer-friendly products and services, driving down prices and increasing competition. The government's delay in implementing open banking, however, has left consumers vulnerable to high fees and limited options. The reliance on five large institutions for financial services could foster an environment where these institutions become too big to fail. This can lead to a lack of incentives for innovation and improvement, as well as increased risks for consumers. The Canadian financial sector is heavily regulated, which means that consumers have some level of protection. However, without open banking, consumers remain vulnerable to the whims of the Big Six, who can charge high fees and provide limited services.
Raising Rates with Competitors
Some competitors already offer significantly higher interest rates than the Big Six. Wealthsimple, a fintech company, has promised its customers 2.4% on their savings accounts, compared to 0.2% for regular banks. Without open banking, consumers are unable to easily switch to these competitors, as it would require more effort due to a lack of data portability. For those who do not have access to information due to lack of competition, they can be stuck paying fees and earning less on savings.
How Open Banking Works
While open banking has not been implemented in Canada, the underlying technology is well-established. APIs enable secure and standardized data sharing, allowing customers to share their financial data with third parties. These APIs allow customers to have a comprehensive view of their financial data, streamlining processes such as budgeting and financial planning. Open banking can also lead to increased innovation and new financial services, as startups and fintech companies are able to develop new products and services that cater to the needs of consumers. By enabling data sharing, open banking can lead to a more transparent and consumer-friendly financial system.
Taking Action: Steps Toward Open Banking
Advocates for open banking in Canada have called on the government to take action. There is a growing movement to call on the federal government to accelerate the implementation of open banking, as well as to encourage regulators and financial institutions to embrace this new model of financial services. Canadians can make their voice heard by demanding open banking through social media, petitions, and other forms of advocacy. Canadians can also take steps to support and advocate for open banking, including increasing awareness about the benefits of open banking, engaging with policymakers, and supporting organisations and initiatives that promote open banking. By taking these steps, Canadians can play a crucial role in driving the adoption of open banking and fostering a more competitive and consumer-friendly financial system. Canadians can take the following steps to advocate for open banking:
- Sign petitions supporting the implementation of open banking in Canada.
- Engage with policymakers by sending letters, making phone calls, and participating in consultations to voice their support for open banking.
- Participate in public consultations and forums to share their views and experiences regarding financial services and the need for open banking.
- Support fintech companies and other organisations that promote open banking and offer innovative financial products and services.
Watch the Reel
Questions readers ask
What exactly is open banking and how does it differ from traditional banking?
Open banking is a system where financial data is shared securely and electronically with the customer's consent. Traditional banking, on the other hand, relies on established practices and services controlled by large institutions. This sharing is done through secure APIs, allowing for more interchangeable and portable financial products and services. Essentially, it gives consumers more control over their financial data and allows them to share this information with third parties, such as fintech companies, for better deals and more choices.
How does open banking empower consumers in their financial decisions?
Open banking empowers consumers by giving them control over their financial data. They can share this data with third parties through secure APIs, which allows them to compare products and services, negotiate better terms, and access a wider range of financial products. This leads to a more competitive and transparent financial landscape, where consumers have more choices and can make more informed decisions.
What are the potential risks for consumers in the current Canadian banking system?
The current Canadian banking system, dominated by the Big Six banks, can pose risks for consumers. These risks include higher fees, limited service options, and reduced innovation. The lack of competition can create an environment where banks prioritize their own interests over those of their customers. This is why open banking, which promotes competition and consumer choice, is seen as a potential solution.
What are the benefits of open banking, as seen in other countries like the UK and Australia?
In countries like the UK and Australia, open banking has led to significant benefits. The UK, for example, saw average annual savings of £400 per family due to increased competition and the ability of consumers to make more informed decisions. In Australia, open banking has led to more competition, innovation, and a more transparent and consumer-focused system. These benefits highlight the potential of open banking to disrupt the traditional banking model and create a more consumer-friendly financial landscape.
Why has Canada been slow to implement open banking?
Canada has been slow to implement open banking despite promises from leaders like Justin Trudeau and Chrystia Freeland. The federal government has repeatedly delayed the implementation, and as of now, there is no clear timeline for when open banking will be a reality in Canada. This delay has been met with criticism, as open banking could potentially disrupt the dominance of the Big Six banks and create a more competitive and consumer-focused financial landscape.
How does the UK's open banking model differ from Canada's current banking model?
The UK's model is mandated by the government, which allows for increased competition and savings for consumers. In contrast, Canada's banking model is dominated by a few large institutions, leading to potential risks for consumers. The UK's model allows consumers to share their financial data with third parties, leading to a more competitive and transparent financial landscape. Canada's current model, on the other hand, relies on established practices and services controlled by large institutions, which may not always be the most consumer-friendly.
Related deep dives
Similar reads based on topic and creator.
Recent articles
Fresh deep dives from the latest Reels we unpacked.
Comments
Be the first to comment.